Roof Insurance Claims in Lexington
Understand the roof assessment, deductible and payment terms after a storm. Roofing guidance for Lexington owners, with Oklahoma Insurance Department resources.
Separate the Roof Work From the Coverage Decision
A storm can create a roofing problem, while the insurance policy decides whether that loss is covered and how payment is calculated. A roof inspection establishes condition and helps define the work. It does not replace the insurer’s coverage decision.
The Oklahoma Insurance Department explains the differences between replacement cost and actual cash value and recommends attention to temporary protection and claim information after severe weather. The actual policy, deductible and loss facts control the claim.
Roof Claim Terms That Change the Budget
| Term | What it means | Why it matters |
|---|---|---|
| Deductible | The policyholder’s responsibility under the applicable policy terms | It affects the owner’s out-of-pocket amount |
| Replacement cost | A settlement basis tied to covered replacement cost, subject to the policy | Payment conditions and limits still apply |
| Actual cash value | A value that accounts for depreciation under the policy | The payment can be less than the cost of a new roof |
| Recoverable depreciation | An amount potentially payable later under qualifying policy terms | The insurer’s conditions and documentation requirements control release |
Roofing After a Storm
Keep people safe and limit further loss
Stay clear of unsafe areas. Suitable temporary protection can reduce exposure while the roof and claim are assessed.
Assess the actual roof
The roofer checks damage, surrounding condition and the work required. Existing photos, a known storm date and what you noticed help provide context.
Let the claim and roof scope meet accurately
The insurer assesses coverage and payment. The roofing work still needs to reflect the measured roof, damage and underlying conditions.
What a Storm Record Can and Cannot Establish
A NOAA report describes an event at a recorded location and time. It can help place a weather event in context. It does not establish that a particular roof was damaged or determine the cause of every mark on a roof.
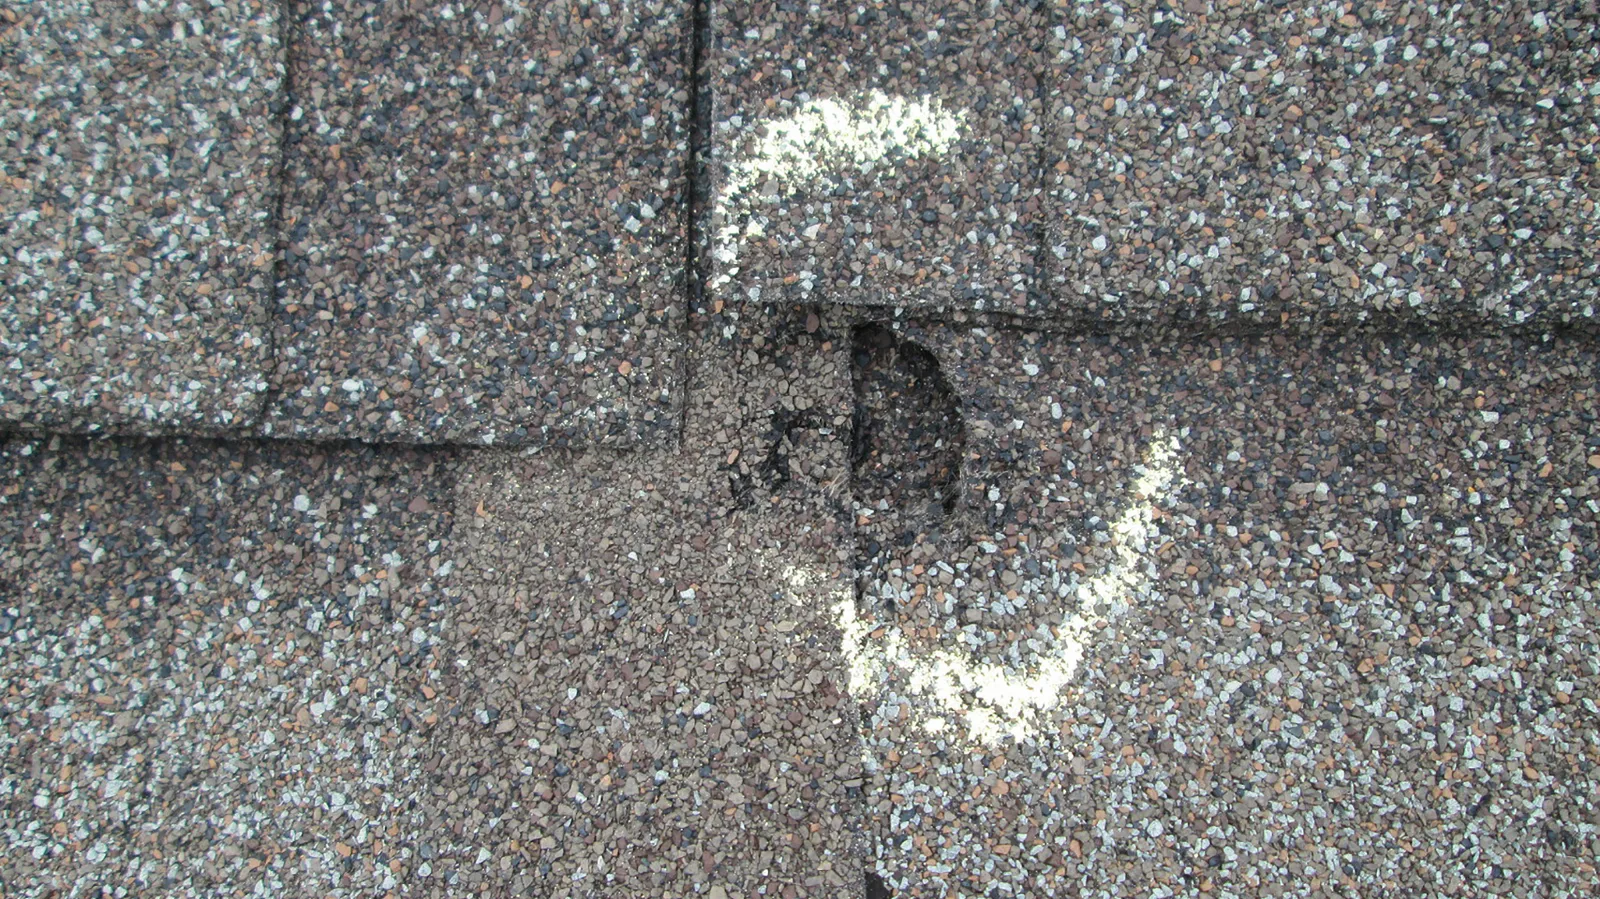
The physical findings, timing, property history and policy terms matter together. Wear, unrelated damage and owner-selected upgrades can be treated differently from a covered storm loss.
Roof Insurance FAQs in Lexington
Will insurance replace an old roof?
Age or wear alone does not establish a covered loss. The cause, damage and policy terms decide whether the insurer owes for repair or replacement.
Does a repair price above the deductible guarantee coverage?
No. Cost and deductible do not establish that the cause is covered or that all proposed work is payable under the policy.
Can the roofing work change after tear-off?
Yes. Concealed damage can change the physical scope. Any effect on a claim still depends on the policy and the insurer’s handling of the actual findings.